So today, editors at Forbes published yet another train-wreck of flawed thinking by Tim Worstall. In The Cause of the Eurozone Crisis Was the Euro: The Solution Is Abolition of the Euro, Worstall tries hard to call for an end to the Euro by blaming its existence for the cause of a what he calls the Eurozone Crisis, which likely he means the the Euro Banking Crisis of 2008 the Greek Lawgivers' Debt Crisis of 2010-2015.
Seriously, I don't understand why Worstall doesn't find another line of work besides trying to write about economies and economics (see more on Tim Worstall right here on Bizarro Theater),
Mundell's Optimum Currency Area Theory is one where an authority can stabilize employment and prices over a well-defined region. According to Mundell himself:
In the work, Mundell cites two who he believes has captured the essence for defining the optimum currency area — Meade and Scitovsky.
Mundell wrote at a time when countries had fixed exchange rates with bank cash convertible to gold while many called for floating exchange rates with irredeemable cash. Mundell proposed his theory as an attempt to explain international disequilibrium caused by balance-of-payments crises under fixed exchange rates and price fixing by legislators (rigid wage and price levels).
Mundell believed that countries with trade surpluses whose leaders capped bank credit caused unemployment for those living in trade deficit countries because leaders of trade deficit countries had to shrink their economies to restore the imbalance.
Whether one banking system shared among a few countries or countries each with their own banking systems, according to Mundell, the fix for regional disparities is for trade surplus countries to inflate (add bank credits) —
So, absent the will to inflate by region in the Euro zone, the Euro zone ought to break up and let floating exchange rates do their work — force prices up of foreign goods as expressed in one's own bank cash.
Read more ...
Seriously, I don't understand why Worstall doesn't find another line of work besides trying to write about economies and economics (see more on Tim Worstall right here on Bizarro Theater),
"Even a cursory glance at the economics of this field, optimal currency areas (founded by Robert Mundell) tells us that over such disparate economies a single currency just isn’t going to work." ~ Tim WorstallWorstall seems not to understand Mundell's Optimum Currency Area Theory at all. Mundell included his theory in a textbook titled International Economics, (1968, pp. 177-186).
Mundell's Optimum Currency Area Theory is one where an authority can stabilize employment and prices over a well-defined region. According to Mundell himself:
- "If the case for flexible exchange rates is a strong one, it is, in logic, a case for flexible exchange rates based on regional currencies, not on national currencies. The optimum currency area is the region."
- "If the world can be divided into regions within each of which there is factor mobility and between which there is factor immobility, then each of these regions should have a separate currency which fluctuates relative to all other currencies."
- "The argument works best if each nation (and currency) has internal factor mobility and external factor immobility."
- "But if regions cut across national boundaries or if countries are multiregional, then the argument for flexible exchange rates is only valid if currencies are reorganized on a regional basis."
In the work, Mundell cites two who he believes has captured the essence for defining the optimum currency area — Meade and Scitovsky.
- "In both cases [Meade's; Scitovsky's ] it is implied that an essential ingredient of a common currency, or a single currency area, is a high degree of factor mobility;"
- "...neither writer disputes that the optimum currency area is the region-defined in terms of internal factor mobility and external factor immobility-but there is an implicit difference in views on the precise degree of factor mobility required to delineate a region."
According to László Andor, European Commissioner for Employment, Social Affairs and Inclusion, in his speech titled Labour Mobility in the EU: Challenges and Perspectives for a Genuine European Labour Market, Europeans have the necessary ingredient of labor mobility.
Free movement of workers began in 1968. Today, it encompasses the labor markets of 28 Member States of the EU and every Eurozone country.
EU nationals have the right to look for work and take up employment in another Member State and to receive assistance from the employment services in the host country when looking for a job.
Countries experiencing the highest increase in labor outflows to other EU countries in 2011-12 were Greece, Spain, Ireland, Hungary and Latvia. Labor outflows went mostly to Germany, Austria and the UK.
So according to Mundell and his theory, the European Central Bank (ECB) ought to make more credit available in Germany, thus pushing up prices in Germany to remove the demand of Greeks from buying German products. With Greek demand for German goods cut by being priced out, Greeks would then produce the alike, substitute goods on lower prices (lower wages), thus taking up unemployment slack in Greece.
But the problem has been the lawgivers in countries like Greece. As wages are prices, they have kept wages up through massive fake-work, make-work government programs, pensions and welfare. Greeks had been living through a credit bubble, a public sector credit bubble and not a private sector. When that bubble burst — Greek lawgivers couldn't borrow without bailouts — Greeks suffered at the hands of lawgivers rather than commercial bankers.
For those who doubt that Greek lawgivers haven't been the source of the problems for the Greeks, have a look at GREXIT IS NO EXIT. Nigerians export more than three times as much as the Greeks, but only import 1.34 times as much as the Greeks.
So how do the Greeks do it? How do the Greeks pay for those imports? Their lawgivers have borrowed year after year to pay for government agency workers, pensioners and welfare collectees who, in turn, take their Euro borrowings and buy imports from those of other Eurozone countries.
In the countries hit hardest by the Euro Banking Crisis, their problems have been caused by lawgivers borrowing to keep afloat phony economies and thus hampering price discovery. As well, by Mundell's theory, those countries within the Eurozone experiencing trade surpluses need to have their regional central bankers rediscount more and thus pump more credit into those countries, which presumably would jack up prices relative to the Eurozone trade deficit countries. By Mundell's theory, it doesn't matter if Germany and Greece are separate countries as long as the countries operate under the same exchange rate and have factor mobility.
Mundell also said, "Similarly, if factors are mobile across national boundaries, then a flexible exchange system becomes unnecessary, and may even be positively harmful, as I have suggested elsewhere."
The Euro is a "gold" standard - one rate for an internal common market with factor mobility that requires lawgivers to adjust policy to that standard. The price of that Euro "gold" standard relative to the outside world (other banking systems' cash) fluctuates.
But the problem has been the lawgivers in countries like Greece. As wages are prices, they have kept wages up through massive fake-work, make-work government programs, pensions and welfare. Greeks had been living through a credit bubble, a public sector credit bubble and not a private sector. When that bubble burst — Greek lawgivers couldn't borrow without bailouts — Greeks suffered at the hands of lawgivers rather than commercial bankers.
For those who doubt that Greek lawgivers haven't been the source of the problems for the Greeks, have a look at GREXIT IS NO EXIT. Nigerians export more than three times as much as the Greeks, but only import 1.34 times as much as the Greeks.
So how do the Greeks do it? How do the Greeks pay for those imports? Their lawgivers have borrowed year after year to pay for government agency workers, pensioners and welfare collectees who, in turn, take their Euro borrowings and buy imports from those of other Eurozone countries.
In the countries hit hardest by the Euro Banking Crisis, their problems have been caused by lawgivers borrowing to keep afloat phony economies and thus hampering price discovery. As well, by Mundell's theory, those countries within the Eurozone experiencing trade surpluses need to have their regional central bankers rediscount more and thus pump more credit into those countries, which presumably would jack up prices relative to the Eurozone trade deficit countries. By Mundell's theory, it doesn't matter if Germany and Greece are separate countries as long as the countries operate under the same exchange rate and have factor mobility.
Mundell also said, "Similarly, if factors are mobile across national boundaries, then a flexible exchange system becomes unnecessary, and may even be positively harmful, as I have suggested elsewhere."
The Euro is a "gold" standard - one rate for an internal common market with factor mobility that requires lawgivers to adjust policy to that standard. The price of that Euro "gold" standard relative to the outside world (other banking systems' cash) fluctuates.
Mundell wrote at a time when countries had fixed exchange rates with bank cash convertible to gold while many called for floating exchange rates with irredeemable cash. Mundell proposed his theory as an attempt to explain international disequilibrium caused by balance-of-payments crises under fixed exchange rates and price fixing by legislators (rigid wage and price levels).
Mundell believed that countries with trade surpluses whose leaders capped bank credit caused unemployment for those living in trade deficit countries because leaders of trade deficit countries had to shrink their economies to restore the imbalance.
Whether one banking system shared among a few countries or countries each with their own banking systems, according to Mundell, the fix for regional disparities is for trade surplus countries to inflate (add bank credits) —
- "In a currency area comprising different countries with national currencies, the pace of employment in deficit countries is set by the willingness of surplus countries to inflate."
- "Unemployment could be avoided in the world economy if central banks agreed that the burden of international adjustment should fall on surplus countries, which would then inflate until unemployment in deficit countries is eliminated"
- "But in a currency area comprising many regions and a single currency, the pace of inflation is set by the willingness of central authorities to allow unemployment in deficit regions."
So, absent the will to inflate by region in the Euro zone, the Euro zone ought to break up and let floating exchange rates do their work — force prices up of foreign goods as expressed in one's own bank cash.
At the end Mundell concludes, "...the optimum currency area is the world, regardless of the number of regions of which it is composed." By that Mundell means there should be one money and balance of payments would adjust regional difference. In short, Mundell means something like gold as money would be the ideal for the world over.
Legally, Europeans have labor mobility. Culturally, whether they move or not is another matter (see: On the Move, The Economist).
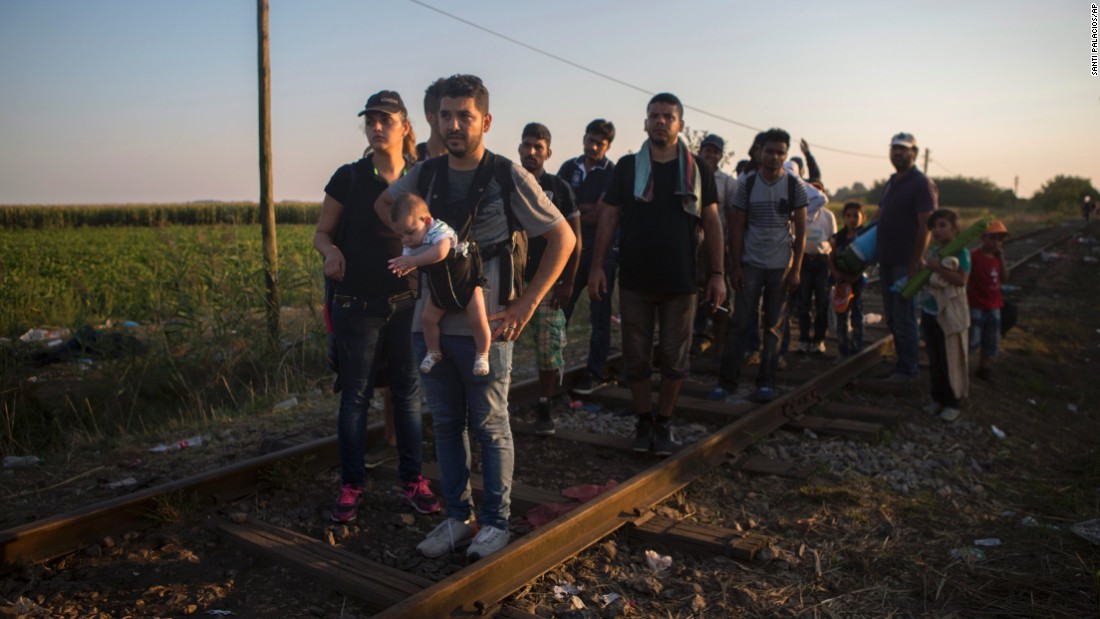
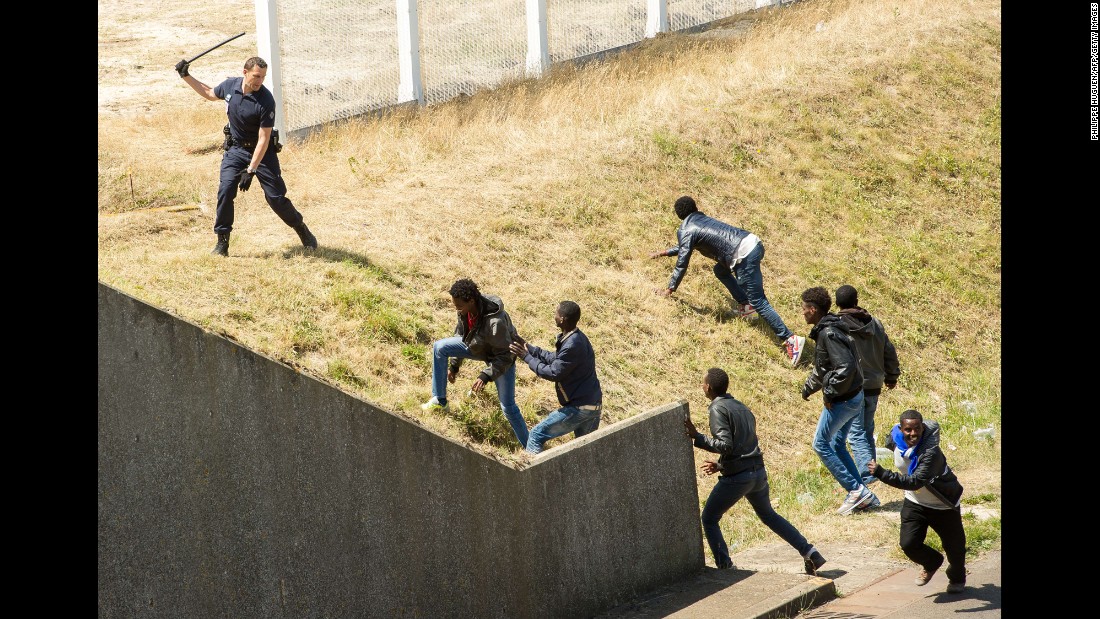
Hordes of illegal aliens, many claiming to be refugees, don't seem to have a labor mobility hang up. For more on the horde invading Europe, check out 2015 EUROPEAN REFUGEE CRISIS. FLEEING THE FAILURES OF TOTALITARIANISM, BUT FAILING TO EMBRACE BETTER WAYS.
Legally, Europeans have labor mobility. Culturally, whether they move or not is another matter (see: On the Move, The Economist).
Hordes of illegal aliens, many claiming to be refugees, don't seem to have a labor mobility hang up. For more on the horde invading Europe, check out 2015 EUROPEAN REFUGEE CRISIS. FLEEING THE FAILURES OF TOTALITARIANISM, BUT FAILING TO EMBRACE BETTER WAYS.


