Tuesday, September 8, 2015

THE 2010-2015 GREEK LAWGIVERS' CRISIS, THE EURO AND CURRENCY AREAS. SHOULD THE EURO ZONE BREAK APART?

So today, editors at Forbes published yet another train-wreck of flawed thinking by Tim Worstall. In The Cause of the Eurozone Crisis Was the Euro: The Solution Is Abolition of the Euro, Worstall tries hard to call for an end to the Euro by blaming its existence for the cause of a what he calls the Eurozone Crisis, which likely he means the the Euro Banking Crisis of 2008 the Greek Lawgivers' Debt Crisis of 2010-2015.


Seriously, I don't understand why Worstall doesn't find another line of work besides trying to write about economies and economics (see more on Tim Worstall right here on Bizarro Theater),
"Even a cursory glance at the economics of this field, optimal currency areas (founded by Robert Mundell) tells us that over such disparate economies a single currency just isn’t going to work." ~ Tim Worstall
Worstall seems not to understand Mundell's Optimum Currency Area Theory at all. Mundell included his theory in a textbook titled International Economics, (1968, pp. 177-186).

Mundell's Optimum Currency Area Theory is one where an authority can stabilize employment and prices over a well-defined region. According to Mundell himself:
  • "If the case for flexible exchange rates is a strong one, it is, in logic, a case for flexible exchange rates based on regional currencies, not on national currencies. The optimum currency area is the region."
  • "If the world can be divided into regions within each of which there is factor mobility and between which there is factor immobility, then each of these regions should have a separate currency which fluctuates relative to all other currencies."
  • "The argument works best if each nation (and currency) has internal factor mobility and external factor immobility."
  • "But if regions cut across national boundaries or if countries are multiregional, then the argument for flexible exchange rates is only valid if currencies are reorganized on a regional basis."

In the work, Mundell cites two who he believes has captured the essence for defining the optimum currency area — Meade and Scitovsky.
  • "In both cases [Meade's; Scitovsky's ] it is implied that an essential ingredient of a common currency, or a single currency area, is a high degree of factor mobility;"
  • "...neither writer disputes that the optimum currency area is the region-defined in terms of internal factor mobility and external factor immobility-but there is an implicit difference in views on the precise degree of factor mobility required to delineate a region."
According to László Andor, European Commissioner for Employment, Social Affairs and Inclusion, in his speech titled Labour Mobility in the EU: Challenges and Perspectives for a Genuine European Labour Market, Europeans have the necessary ingredient of labor mobility.

Free movement of workers began in 1968. Today, it encompasses the labor markets of 28 Member States of the EU and every Eurozone country.

EU nationals have the right to look for work and take up employment in another Member State and to receive assistance from the employment services in the host country when looking for a job.

Countries experiencing the highest increase in labor outflows to other EU countries in 2011-12 were Greece, Spain, Ireland, Hungary and Latvia. Labor outflows went mostly to Germany, Austria and the UK.

So according to Mundell and his theory, the European Central Bank (ECB) ought to make more credit available in Germany, thus pushing up prices in Germany to remove the demand of Greeks from buying German products.  With Greek demand for German goods cut by being priced out, Greeks would then produce the alike, substitute goods on lower prices (lower wages), thus taking up unemployment slack in Greece.

But the problem has been the lawgivers in countries like Greece. As wages are prices, they have kept wages up through massive fake-work, make-work government programs, pensions and welfare. Greeks had been living through a credit bubble, a public sector credit bubble and not a private sector. When that bubble burst — Greek lawgivers couldn't borrow without bailouts — Greeks suffered at the hands of lawgivers rather than commercial bankers.

For those who doubt that Greek lawgivers haven't been the source of the problems for the Greeks, have a look at GREXIT IS NO EXIT. Nigerians export more than three times as much as the Greeks, but only import 1.34 times as much as the Greeks.

So how do the Greeks do it? How do the Greeks pay for those imports? Their lawgivers have borrowed year after year to pay for government agency workers, pensioners and welfare collectees who, in turn, take their Euro borrowings and buy imports from those of other Eurozone countries.

In the countries hit hardest by the Euro Banking Crisis, their problems have been caused by lawgivers borrowing to keep afloat phony economies and thus hampering price discovery. As well, by Mundell's theory, those countries within the Eurozone experiencing trade surpluses need to have their regional central bankers rediscount more and thus pump more credit into those countries, which presumably would jack up prices relative to the Eurozone trade deficit countries. By Mundell's theory, it doesn't matter if Germany and Greece are separate countries as long as the countries operate under the same exchange rate and have factor mobility.

Mundell also said, "Similarly, if factors are mobile across national boundaries, then a flexible exchange system becomes unnecessary, and may even be positively harmful, as I have suggested elsewhere." 

The Euro is a "gold" standard - one rate for an internal common market with factor mobility that requires lawgivers to adjust policy to that standard. The price of that Euro "gold" standard relative to the outside world (other banking systems' cash) fluctuates.

Mundell wrote at a time when countries had fixed exchange rates with bank cash convertible to gold while many called for floating exchange rates with irredeemable cash. Mundell proposed his theory as an attempt to explain international disequilibrium caused by balance-of-payments crises under fixed exchange rates and price fixing by legislators (rigid wage and price levels).

Mundell believed that countries with trade surpluses whose leaders capped bank credit caused unemployment for those living in trade deficit countries because leaders of trade deficit countries had to shrink their economies to restore the imbalance.

Whether one banking system shared among a few countries or countries each with their own banking systems, according to Mundell, the fix for regional disparities is for trade surplus countries to inflate (add bank credits) —
  • "In a currency area comprising different countries with national currencies, the pace of employment in deficit countries is set by the willingness of surplus countries to inflate."
  • "Unemployment could be avoided in the world economy if central banks agreed that the burden of international adjustment should fall on surplus countries, which would then inflate until unemployment in deficit countries is eliminated"
  • "But in a currency area comprising many regions and a single currency, the pace of inflation is set by the willingness of central authorities to allow unemployment in deficit regions."
Under floating rates with irredeemable bank cash, those living in the trade deficit countries would need to pay more for foreign cash of trade surplus countries until BOP equalized. Thus, all inflation would be unneeded as is the fix for disparities between regions under the same banking system.

So, absent the will to inflate by region in the Euro zone, the Euro zone ought to break up and let floating exchange rates do their work — force prices up of foreign goods as expressed in one's own bank cash.


At the end Mundell concludes, "...the optimum currency area is the world, regardless of the number of regions of which it is composed." By that Mundell means there should be one money and balance of payments would adjust regional difference. In short, Mundell means something like gold as money would be the ideal for the world over.

Legally, Europeans have labor mobility. Culturally, whether they move or not is another matter (see: On the Move, The Economist).
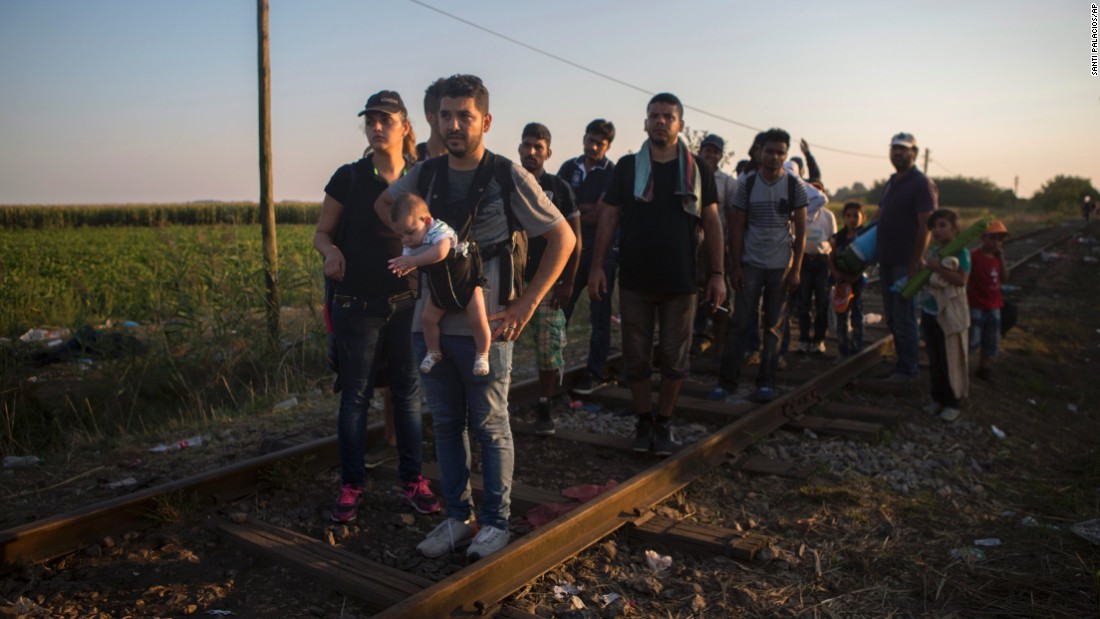


Hordes of illegal aliens, many claiming to be refugees, don't seem to have a labor mobility hang up. For more on the horde invading Europe, check out 2015 EUROPEAN REFUGEE CRISIS. FLEEING THE FAILURES OF TOTALITARIANISM, BUT FAILING TO EMBRACE BETTER WAYS.


Read more ...

Wednesday, July 29, 2015

IT'S TIME TO END THE EU AND EURO MADNESS

The Greek Legislators Overspending Crisis has shown the world something that few politicians from the various countries of Europe want to acknowledge. It's time to end  the Euro zone and as importantly, end the EU. Everyone knows this but politicians and the simple-minded who depend on politicians to eat.


This is what should happen:
  1. The Germans should exit the Euro and the EU and then create the new Mark zone and the new Hanseatic League.
  2. The British should exit the EU. 
  3. The Irish should exit the Euro and the EU and then the British and Irish should create the new Pound zone and the new Commonwealth.
  4. The French and Italians should form the new Euro, call it the lira/livre and create the new Roman Europe.
  5. Belgium should break up into Walloonia and Flanders.
  6. South Tyrol should revert to Austria.
The Deutsche should create the new Mark zone. The Deutsch should invite these countries into the new Mark zone: Austria, Nederlands, Czech Republic, Finland, Estonia, and Belgian Flanders along with maybe Slovakia and Slovenia.

As a true free trade zone rather than a reciprocity zone, the new Hanseatic League should invite these countries to participate: Denmark, Sweden, Norway, Poland and Switzerland. As well, the new Hanseatic League could invite Latvia, Lithuania, and Hungary.

The new Hanesatic League ought to work out trade deals with the new Pound Commonwealth as well as with the Russian-Belarus Trading bloc.

The French and Italians should form the new lira/livre and new United Roman Europe. Likely, the countries joining the French and Italians in new lira/livre zone and New Roman Europe could be: Spain, Portugal, Greece, Malta and the whole of Belgium, if Belgium fails to split into the new Wallonia and the new Flanders.

The British ought to do what is in their best interest, revive their commonwealth and in so doing, entering in reciprocity trade agreements (wrongly and deceptively called "free trade") with the Americans, Canadians, Kiwi, Australians, and Hindians.

The foregoing would truly fix Europe for Europeans and better the world.

The idea of the EU itself arose from unscientific, superstitious thinking from the late 1940s to 1970s (see: the Schuman Declaration). The EU is as antiquated as the United Nations is.

By the time the EU coalesced, globalization was underway. The EU was obsolete before the ink dried on the signed documents.

Should the Germans leave the Euro and the EU, that giant sucking sound that you will hear is the vortex the Germans will create, which will pull along a slew of countries with politicians smarter than the French and Italians.

Following the Germans likely will be the Dutch, the Austrians, the Finns and the Estonians. Likely, the Czechs, the Slovaks, the Slovenes along with the Danes, the Swedes, the Poles and the Swiss will want to be a part of anything the Germans will devise.

Should the Germans up and go, so too will the Brits. Likely, the Brits would cozy up to a German run trade bloc before the Brits will hook up with the French and Italians.

The French and the Italians will collapse into each other's arms. Expect the Spaniards, the Portuguese, the Greeks, the Maltese, and maybe the Belgians to join them.


Likely, the Irish will be too stupid and join the French and Italian bloc even though the Irish mostly sell and buy from the Brits.

Brits need to awaken and leave the EU behind anyway, regardless of how the Germans and French settle this. Brits are missing out on a FTA with the Americans, the Canadians, the Aussies and the Kiwis. The future is in the Pacific and not found on a backwater peninsula at the far west end of Asia.

Gauls, other Latin Europeans and the Greeks think differently from Germanic Europeans. The former are fooling themselves if they can ever be the latter.

The difference between the Gallo-Latins along with the Greeks to the Germanics is alike to the difference between helpless school children and axe-wielding warrior men, between the effeminate and the manly, between those who teach because they can't do and those who can do, between socialists and individualists.

All should hope Europe blows up because of the Greek legislators' overspending. crisis.

Read more ...

Monday, July 13, 2015

MY BIG FAT GREEK STUPIDITY. THE TSIPRAS AND VAROUFAKIS GREEK COMEDY SHOW WRAPS UP.

Well, it looks like shooting almost has wrapped up for the new comedy, My Big Fat Greek Stupidity starring Alex Tsipras and Angie Merkel, co-starring Yanny Varoufakis, Wolfie Schäuble, Donnie Tusk, Mario Draghi and many more!


First, if you are shocked by the outcome between Alexis Tsipras, the prime minister of Greece and the Eurogroup ministers, who are the finance ministers of the Euro zone, you should not be. Had you been a consistent reader of mine, you would have known all along what was happening between the Greeks and the leaders of the Euro zone, the EU and the IMF.

In these works, I shared with you reckless spending of Greek law givers compared to other countries with alike economies — the Czech Republic and Portugal. I shared with you what the Greeks needed to do — cut per capita spending a paltry 4.4% down to $3,913.33 so Greek law givers could pay a mere €6.36 billion a year of debt, roughly 1.9% of total debt owed and 2.6% of GDP, without GDP growth. I shared with you that Greek law givers had to pay €63.58 billion worth of debt over ten years  that Greek law givers borrowed to pay generously, for salaries and pensions of government workers and not €330 billion falsely cited by the ill-informed in effort to reduce total debt-to-GDP to 110%.

I shared with you why Greeks held no cards — Greece GDP is a rounding error — 1.84% of the total Euro zone GDP less the Greek GDP. That is like throwing two cents on the ground for every Euro in your pocket.

I shared with you that Greek law givers lost any leverage when the ECB shuttered ECB-aligned banks. Since Greek banks have much of their reserves tied to bonds of Greek law givers, the acts of Tsipras and Varoufakis-led SYRIZA impaired those reserves. Impaired reserves required emergency liquidity assistance (ELA) from the European Central Bank (ECB).

When the ECB cut off ELA to Greek banks, Greek bankers were forced to close. Closing the banks effectively cut off the metaphorical water supply to Greeks.  Litiming ATM withdrawals to €60 a day with no other banking services seized up the machinery known as commerce.

As well, I shared with you the big bomb that is going to drop on July 20. Greek law givers owe €3.5 billion (US$3.9 billion) to the ECB. That date marks the final call in this poker game.

Many have called for the Greeks to stiff their European partners and have their banking system return to the drachma.  In effect, many wanted to see the Greeks betray the European project. 

Why would the Greeks seek to exit the Euro zone and return to the drachma? If the Greeks have their own banking system with its own cash, how would that change anything for the Greeks? Greeks make very little their trade partners want to buy. 

The top export for Greeks consists of refined petroleum products. For the latest year (2012) available, Greeks exported $11.812 billion worth of refined petroleum products, which comprised 34.9% of all Greek exports.
  
The top importers of Greek products are near-penniless Italians (7.96%), penniless Cypriots (4.75%), penniless Spaniards (2.65%), near-penniless Frenchmen (2.56%) and penniless Russians (1.93%). 

Yet fools believe it is the Eurogroup ministers who are betraying the European project. In spite of what neither politician nor businessman but lifetime academician Paul Krugman has claimed, the Greeks have been the ones betraying Europeans.

In a show of generous unity by those leading the European project, the Greeks were bailed out not once, but twice, in 2010 and 2012. The socialist-communist SYRIZA came to power and reneged on those bailout deals. As well, since 2010, Greek law givers have failed to meet conditions they agreed upon to get Greeks and their economy in line with the European project.

Greeks have been living under the delusion of a massive credit bubble, one fostered not by bankers in Greece, but by Greek legislators. That bubble needs to be popped, permanently.

For years, since socialist party leader, Andreas Papandreou, the Greeks had been betraying the European project. Papandreou engaged in despotic-like spending, hiring supporters to government jobs. In so doing, Papandreou created a massive spoils system built around government using funds from the EU to pay for this system. And when the opposition party came to power, they grew the system even bigger.

This is why are the Greeks in trouble. For decades, Greek law givers created a bubble economy. Instead of the bubble economy being blown ever bigger by private-sector inflation — bankers' credit — Greek law givers created their bubble economy through public-sector credit.

By creating government jobs that ought not to exist and by overpaying for those jobs, Greek law givers kept their credit bubble inflated.

Varoufakis along with Tsipras and the rest of the jokers from SYRIZA are like all other law givers. They seized power by promises of more spending — ending austerity.

Varoufakis, Tsipras and all of the SYRIZA jokers wanted to spend beyond their will to tax. That is why they have been begging for five months to get more bailout cash and not pay on debt already accrued for law givers' spending largess.

Tsipras lost. Tsipras and his game-playing, cycle-riding sidekick lacked leverage. The ascension of SYRIZA to power was the first referendum and only one that should have been held. 

Tsipras worst move was holding and encouraging a No-Vote referendum to reject a new deal being offered by Eurogroup ministers. A yes-vote win would have forced Tsipras to cave into demands. 

The actual no-vote win forced Tsipras to present his plan. The Eurogroup ministers called him on it. In short, the no-vote meant no more delay tactics could be played.

The fix for Greeks is deflation. Greek law givers need to stop trying to create a phony economy through borrowing. 

Greeks need to devalue. They have needed to devalue for a long time. 

Their prices are too high. Their prices are too high because law givers borrow to spend on wages and pensions for government workers. All should know that wage rates are prices.

The Euro isn't going to fall much relative to the cash of other banking systems such as the U.S. dollar, the British pound, the Norwegian krone or the Swiss Franc. So to devalue, prices need to fall. Prices won't fall until Greek law givers cut the sum of credit they introduce into the Greek economy.

And so, to remain part of the European project, Greek law givers must give up their spoils system and bring Greeks into the 21st century.

Part of the new deal, Greek law givers must do these acts by Wednesday:
  • make standard their VAT tax rates
  • increase the retirement age for law-givers provided pensions to 67 by 2022
  • legalize automatic spending cuts of Greek law givers try to abandon budget targets
  • end the spoils system
If Greek law givers can do these acts, then formal talks can begin between Tsipras and the Eurogroup ministers for a new, permanent bailout deal of €86 billion.

Greek law givers must cut their per capita spending. That is what they have been asked to do. If Greek law givers do so, they will get their deal reworked. 

If Greek law givers agree, Greece will strengthen and the Euro gets better. If Greek law givers reject, Greece will exit and the Euro will strengthen. Either outcome is good for the Euro. Only one outcome is good for the Greeks — staying in the Euro, cutting Greek law givers' power.

The problem for Greeks is the same problem everyone suffers the earth over. Over many years bad law givers have leveraged doling welfare to gain power and keep it. With power, law givers have then created a horrible culture — codified law — of bad design, which unsurprisingly has led them to their final destination of failure. 

Greek law givers let their debt grow beyond their ability to service the interest payments. Their poor decisions led to exponential growth of debt. Per capita spending by Greek law givers is well beyond the size of Greek economy compared to other EU states of alike-sized economies as measured by GDP.

And in spite of what Krugman and others like him wrongly claim, the Eurogroup ministers strive to keep the European project going. They are trying to come up with a plan for short-term financing to help Greek law givers over the next few weeks.

Even if SYRIZA Greek law givers reject this final deal, Greek law givers are on the hook for all kinds of bonds floated in jurisdiction that is not Greece. No matter what, Greeks will be paying taxes to their law givers for those bonds. Greek law givers will pay on those foreign bonds.

In life, when adults have the power to decide, they don't get what they want always, but always, they get what they deserve.

For an up-to-the minute timeline for the SYRIZA-caused crisis, check out the Guardian UK. Be wary about what you believe published there.
Read more ...

Thursday, July 9, 2015

REALITY SMACKS GREEKS. WHAT MUST BE PAID BACK WILL BE PAID BACK.

I've taken heat for stating what all should should have known all along about the so-called Greek crisis, which Greek legislators brought upon all Greeks over many years: What must be paid back will be paid back.

Populist fools everywhere want Greeks to be their Hercules heroes. They want the Greeks to default and stiff the bankers because they have been indoctrinated to believe bankers are evil swindlers who somehow by the very nature of the banking, cheat everyone.

If Greek law givers want to stay in the Euro zone, they must pay back enough of the outstanding debt apportioned over time to reduce cumulative debt-to-GDP to 110%. However much debt that Eurogroup ministers say Greek law givers have up to the full amount will be the sum apportioned.

If Greek law givers don't want to stay in the Euro zone, they won't pay back anything, at least not on bonds sold in Greece under Greek jurisdiction. If that is what Tsipras and his cronies decide, Greeks won't have much of an economy though.

As I have said repeatedly, should the Greeks return to the Drachma, the real austerity will begin. If Tsipras doesn't do as told and if Greek law givers don't do as told, they can enjoy crushing third world poverty under their Drachma.

With a return to the Drachma, voluntarily Greeks will turn their country into a Submerging Market™.

If Greeks don't want to become Argentinians, Venezuelans, Iranians, North Koreans and the like, Greek law givers are going to play ball. Greek law givers will be on the hook for bonds sold outside of Greece and falling under jurisdiction elsewhere. Those obligations are not going away.

Many have heralded Alexis Tsipras, the Greek Prime Minister as a negotiating genius, someone who has played the Eurogroup ministers as if they were fools. That belief is the belief of fools.

Tspiras called for a snap referendum, politicking for a no-vote. Greeks gave him what he wanted, a no-vote. Only in fantasy land did self-confused pundits claim Tsipras would be emboldened with a no-vote, being empowered to dictate terms and conditions to the Eurogroup ministers.

To any clear-minded thinker, it was obvious, with a no-vote, Tsipras straightaway had to put forth his plan. The Eurogroup ministers called him on it. In short, the no-vote meant no more delay tactics could be played.

If Tsipras wanted the Greek banking system out of the Euro, why didn't he announce so on the day of winning election and SYRIZA taking power? Why didn't SYRIZA pass a law the next day to swap Drachma for Euro?

If Tsipras has wanted the Greek banking system out of the Euro all along, why go back to the Eurogroup ministers over five months, becoming a street beggar each time, panhandling for another bailout?

Greek law givers lost any leverage when the ECB shuttered ECB-aligned banks. €60 Euro a day ATM withdrawals with no other banking services seized up the machinery known as commerce.

By cutting off emergency liquidity assistance (ELA) to Greek banks, Greek bankers were forced to close. Closing the banks effectively cut off the metaphorical water supply to Greeks.

Greek banks have much of their reserves tied to Greek law givers. With impaired reserves, Greek bankers relied upon the ELA. Those reserves deteriorated worse precisely because of the Tsipras-led SYRIZA.

Also, there is no way for the leaders of Estonia, Latvia and Lithuania along with Slovakia and Slovenia, leaders who helped their peoples financially atone for the sins of communism, to sell to their citizens that Greeks must stay in the Euro and to do that, they must let the Greeks off the hook for all of their profligate spending.

In an interview with Radio Free Europe's Rikard Jozwiak, Sandra Kalniete, the former Latvian foreign minister and current member of European Parliament had stern words to say about Tsipras and the Greeks.
I would say that, of course, Europe has to show solidarity, but that means that Greece has to go forward with [a] very precise and concrete reform program not only on paper but they have to convince Europeans that they are going to implement it. Because I consider that this isn't fair that countries like Ireland, Spain, Portugal, and Latvia -- we went through [a] reform program. Our people made such sacrifices, and now there comes a nation which received much more from the European Union and international society in credit, and now they are saying that they are not able to reform Greece to make it sustainable. I simply cannot accept it.
I believe the euro can survive without Greece. Greece cannot survive without the euro, that's the dilemma. Of course, every European [is] conscious [of] the geopolitical importance of Greece in an environment which is rather difficult to manage and in front of migration waves which are coming from Syria and Libya, and they are also reaching Greece.  ~ Sandra Kalniete, member of the European Parliament and former Latvian foreign minister
Only a day or so ago, Tsipras foolishly said that a "clash with Europe ... will take ... the euro zone down." Greece GDP is a rounding error — 1.84% of the total Euro zone GDP less the Greek GDP. That is like throwing two cents on the ground for every Euro in your pocket.

On July 20, Greek law makers owe US$3.9 billion. That date marked the final call in this poker game anyway. As it is, the deadbeat socialist-communist SYRIZA legislature already missed a major payment owed to generous creditors.

Read more ...

Wednesday, July 8, 2015

GREEKS HAVE BEEN SERVED A BIG CUP OF ELLINIKOS KAFES FOR THEIR COLD AUSTERITY WINTER AHEAD

Donald Tusk, the European Commission president has served a big cup of Ellinikos Kafes to Greeks (video). While handing them their big mug of Greek coffee to sober up Greeks after years of swilling free-to-them ouzo, Tusk said, "...five days left...the final deadline ends this week."


It has been laughable to read when pitchfork populist bloggers have claimed the Greek Dumb and Dumber, Prime Minister Tsipras and Finance Minster Varoufakis had the upper hand. They never ever had it.

Their stupidest move was to hold that referendum. While ordinary Greeks were misled by Tsipras and Varoufakis to believe they were sending jingle mail to IMF, EFSM and the EU, in fact, they were voting for their own Grecocide.

An especially popular pitchfork populist blogger hailed the referendum as a genius move. He strengthened his silliness with a mantra he has gotten his neophyte readers to parrot — what can't be paid back, won't.

Right from the start, reality has been different — what must be paid back will be paid back. For Greek law givers to remain in the Euro, Greek law givers had to pay their debts.

The winning No-Vote has given the leaders of the Eurogroup the smokescreen they need to squeeze Greeks out of the Euro.

“Party time at the expense of others in Greece has come to an end. Europe and the euro area are surely unprepared to pay for the irresponsible behavior of the new Greek government...You can’t have one country enjoying a feast, overspending and having everyone else pay for it, including our citizens with much lower pensions and wages.” ~ Lithuanian President Dalia Grybauskaite
 “We have a Grexit scenario prepared in detail.” ~ Jean-Claude Juncker, European Commission President
It should have been clear that Greeks needed support from leaders of other small Euro zone economies, the ones who threw off the shackles of the old Soviet system. Yet, it should have been clearer they would never get that support since the peoples of those countries sucked it up for a long time to get themselves in order to be competitive members of the Euro zone and the EU.

Greek law givers caused their own crisis. And Greek law givers couldn't have done so without Greek voters election after election approving of their law givers. Years of borrowing and rolling over debt with new borrowing led Greek law givers beyond the tipping point.

Financially and mathematically, Greeks were in position to pay back enough of their cumulative debt to whittle that debt down to 110% of GDP over ten years. To do so Greek law givers were supposed to declare badly needed so-called structural reforms — cutting spending significantly and by doing, pushing down prices.

In exchange for generous help, Greek law givers had been asked to pay down a mere €6.36 billion a year of debt, which, each year would have been 1.9% of total debt owed and 2.6% of GDP. However, the socialist-communist SYRIZA who came to power as Greek law givers wanted to pay nothing.


Like winter is coming for the fictional world of Game of Thrones, real austerity is coming at last to the Greeks. Whether it's tough austerity through the Euro or extreme austerity through the Drachma, austerity is coming.

The ECB can keep closed their banks forever. So likely, Greeks will be forced into the Drachma. In short, Tsipras (interestingly, Tusk pronounces his name as cheap-ass) and the quitter Varoufakis have misled their Greeks into what will be third world Drachma-austerity.

Right now, Greeks lack the means to pay for oil or natural gas priced on world markets. Greeks lack the means to pay for pharmaceuticals, engineered machinery, engineered materials and of all kinds, cars and trucks, airplanes and well, mostly everything produced by mankind today. Reverting to the Drachma will fail to give Greeks the means.

Winter 2015-2016 is going to be one to be remembered for Greeks. At least they can think fondly upon their no-vote referendum as they burn the last of their furniture to keep warm. They can think of all their Internet supporters in America and elsewhere as the humanitarian aid ship docks in Athens on its way to other third world countries.

In life, for adults who can decide, they don't get what they want always, but always, they get what they deserve.

Kalí týchi!


Read more ...

Monday, June 29, 2015

GREEKS ARE SET TO VOTE TO SEND JINGLE MAIL TO THE IMF, EFSM AND THE EU

When someone can't pay his or her monthly mortgage payment owed the lender (mortgagee) and walks way from that obligation by mailing the house keys to the mortgagee, that someone has pulled a jingle mail trick. In short, the borrower has said to the lender, Here is the pledged collateral, the house. It's yours now. I refuse to pay you.


Why did many so-called homeowners do this during the Banking Crisis in 2008? First, many couldn't pay their mortgage payments from their incomes, though many could. Second, many couldn't refinance their mortgage deals precisely because the likely re-sale price of the house given the current market had fallen below the amount owed on the loan. In banking parlance, that's known as being underwater or being upside-down.

Many Americans who were greedy and nervous, but had the means to pay their mortgages walked away from having property in their improved parcels, turning over those parcels to the original lenders. They didn't like being underwater and paying on a loss. To them, never could they see a future where the economy would recover, house prices would recover and they might at least break even.

So rather than uphold their obligation, many stuffed their house keys into envelopes, called the Midnight Moving Company and dropped off those envelopes in the nearest mailbox as they skipped town. Apologists, mostly anti-capitalists and those jealous of anyone else richer by $50, stepped in and began calling such unscrupulous misdeeds, strategic defaults.

For those Americans with non-recourse mortgages, they faced few consequences from sending off their jingle mail. Lenders were stuck with many houses they couldn't sell. For those houses they could sell, lenders were stuck with losses on the differences between what they lent and what the they could gain in sales on much lower street prices.

The story was different for Americans with recourse mortgages. Those who tried to walk away from their mortgages discovered that lenders had legal standing to sue to have wages garnished and other assets seized.

Many non-recourse jingle mailers claimed that even though they knew they agreed to the terms of their contracts, they believed they had the right to walk away from what they claimed were bad deals. To win the war for supporting minds, these jingle mailers compared their plights to big corporations that write-down billions of dollars of debt and incur losses for shareholders.

An individual agreeing to the terms of the mortgage to gain the funds to buy a house in which to sleep is not the same as enterprisers who have sold bonds to gain funds to buy capital in quest of producing property which they hope to trade a profit.

More so, none were walking away from bad deals. All of the deals were good deals.

In every case, luckily, each borrower found a lender who put forth actual credit in large sums in exchange for mere promises. All of those borrowing gleefully became homeowners and likely many bragged to their friends about their new digs.

In each deal, borrowers received actual funds, typically in the form of bank credits, in trade for promises to pay. None of the deals were contingent upon changing street prices based on the sales of other houses.

To claim bad deals as justification to stiff creditors is mere twisted rhetoric to cover for misdeeds. As well, all those who stuck creditors with jingle mail, walked away from houses upon which they put wear and tear, which of course, is a kind of loss. Of course, those who believed in that way tortured reality to justify their misdeeds. Not surprisingly, noted lefty Keynesian economist Paul Krugman championed jingle mail, at least according to writers of Wikipedia.

Greeks go to the polls on July 5, 2015, to vote on a referendum asking whether their legislators should continue to pay on debts owed to the IMF and the European Financial Stability Mechanism or should legislators stick the keys in the mail and send those running the IMF and EFSM jingle mail.

Since every election is a referendum of sorts, for decades, the majority of Greeks voted yes on referendums approving of their legislators borrowing excessively so legislators could pay for high-paying, make-work government jobs and pensions. All of that borrowing led to legislators spending more than 50% of GDP in many years. Worst of all, all of that borrowing and spending led Greeks to believe they were rich even though that borrowing and spending would cripple the Greek legislators and bring them to their current state, near bankruptcy.

Greeks are much like those underhanded Americans with non-recourse mortgages and incomes to pay their mortgages but who found themselves underwater.

Right now Greeks find themselves underwater. The street price of everything Greeks sell is falling. Yet, Greeks have the income to pay debts. However, Greek legislators don't feel like paying their debts. So, Greeks are being encouraged by their unscrupulous leaders to send jingle mail.

Unlike most Americans who found themselves underwater and who could not renegotiate their deals after the Housing Bubble burst, a bubble caused by the Greenspan-Bernanke Great Inflation, the biggest credit bubble in the history of mankind, Greek law givers can renegotiate their deal. However, those Greek law givers don't want to renegotiate.

As I explain in TSIPRAS AND VAROUFAKIS, THE GREEK DUMB AND DUMBER SEEK TO FORCE GREEKS TO DRINK HEMLOCK, what Greek law givers need to do is cut their per capita spending. That is what they have been asked to do. If Greek law givers do so, they will get their deal reworked. But, Greek law givers still want to live in a bubble.

The Greeks borrowed from lenders to buy a McMansion. And then for decades, Greeks piled on HELOC after HELOC to pay for ongoing parties as they swilled ouzo, munched on baklava and danced to Zorba. And now the Greeks want to run out the back door, stiffing the owners of the catering hall while mailing in the keys.

Read more ...

Wednesday, November 5, 2014

WHEN IRISH EYES ARE SELLING AND BUYING. WHY THE EURO AND NOT THE U.S. DOLLAR? AH THOSE BANKER'S BLUES.

So, Jeremy Warner of the UK's Telegraph caught a performance by the American financial TV broadcaster, CNBC's Joe Kernan (YouTube video) who seemed bemused upon learning the Irish banking system belongs to the Eurozone and not the British.

Warner claims it's "from an economic perspective, it's a very odd state of affairs which isn't obviously doing the country [the Irish] a great deal of good."

The Irish have had overlords since Henry II sent a force in 1171 to control his own Norman knights in their 1169 conquest of Ireland. The Irish overlords of today are German bankers mostly along with French and Italian bankers as well as their respective national politicians who get these bankers to buy sovereign bonds, thus enabling deficit spending and ever weakening the buying power of the Euro.

So why are the Irish beholden to their continental masters and not their former British masters? Here is what the numbers say.

It's true. The Irish import more goods from the Brits than from anyone else. In fact, 38.5% of all their goods come from the UK. The Irish import 1.5 times as much stuff from Brits as they do from their Eurozone friends.

However, the Irish export 2.7 times as much stuff to their Eurozone friends as they do to Brits. With their Eurozone friends, the Irish have a $37.5 billion trade surplus. With their not so beloved Brits, the Irish suffer a -$2.4 billion trade deficit.

Of their Eurozone friends, the Irish hold their best trade position with the Belgians and Luxembourgians. The Irish run a $16.5 billion trade surplus with with the two countries combined, which is 2.5 times better than their trade position with the French or the Germans, their next two biggest trading partners of the Eurozone.

In spite of their -$1.4 billion trade deficit with the Norwegians, mostly for oil, the Irish enjoy a $7.4 billion trade surplus with the banking independents, Swiss, Danish and Swedes, including the Norwegians.

Americans buy more stuff from the Irish than anyone. The Irish sell 21.6% of their goods to Americans. Americans buy 1.4 times as much stuff from the Irish as the Brits do. Americans buy from the Irish 1.5 times as much as Belgians and Luxembourgians combined, 2.4 times as much as the Germans and 3.0 times as much as the French.

The Brits with their Bank of England and British pound whom Kirnan believes should be the banking masters over Irish, engage is substantial trade with those of the Eurozone. A whopping 62.4% of Brit imports come from Eurozone countries while the Brits sell 57.4% of their exports to Eurozone countries.

Eurozone countries hold 77.5% of Brits's net trade position. The BRIC countries of China, India and Russia come in second with 44% of the British's net trade position.

As with the Irish, Americans buy more stuff from Brits than anyone else, although the Germans aren't far behind ($52.4 billion vs $47.5 billion). Brits sell three times as much stuff to the Eurozone players as they do to Americans and Canadians combined.

So, the bigger question becomes why aren't the Irish using the Federal Reserve banking system for theirs and thus the U.S. dollar for their cash? Likewise, why haven't the Brits long ago abandoned the British pound and the Bank of England in favor of the Federal Reserve and the the U.S. dollar or the European Central Bank and the Euro?

Unless the Irish have their own cash, never will the Irish be free. The Irish might as well celebrate the Henry the 8th Tudor re-conquest of Ireland of the 1530s.

Enjoy an little-known Irish export, a quality guitarist, Rory Gallagher.


Read more ...